Market overview and structural significance of the Artificial Intelligence-Powered Supplier Risk Management Market
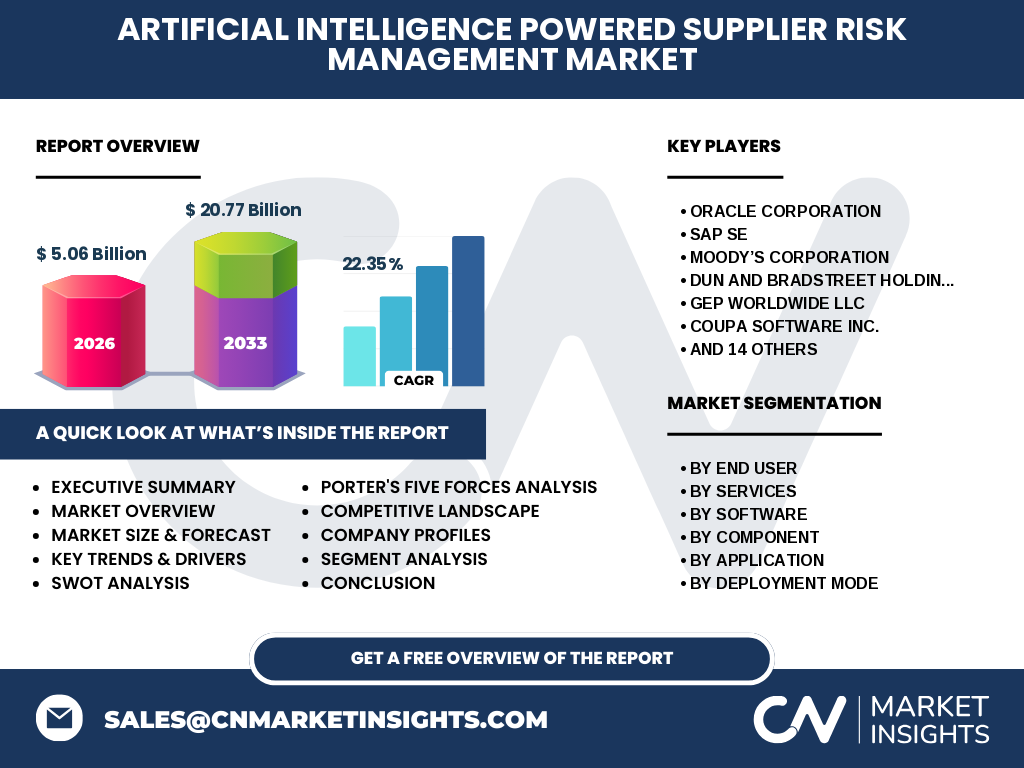
The Artificial Intelligence-Powered Supplier Risk Management Market represents a pivotal evolution in global supply chain governance, valued at $5.06 Billion in 2026. This sector encompasses advanced software and specialized services designed to predict, mitigate, and monitor disruptions caused by geopolitical tensions, raw material shortages, and evolving trade regulations. Corporations increasingly rely on these platforms to secure critical inputs like rare earth elements and semiconductor components, safeguarding operational continuity across complex, multi-tiered manufacturing networks.
What core drivers, restraints, challenges, and opportunities shape the Artificial Intelligence-Powered Supplier Risk Management Market?
Our analysis indicates that structural growth is propelled by escalating compliance mandates, such as the EU Corporate Sustainability Due Diligence Directive, forcing firms to adopt Predictive Risk Analytics Software. However, high initial deployment costs and data privacy concerns among tier-2 suppliers act as primary restraints. Significant opportunities lie in integrating machine learning with IoT-enabled logistics to provide real-time visibility, allowing enterprises to circumvent port congestion and labor strikes before operations stall.
Emerging trends and growth patterns in the Artificial Intelligence-Powered Supplier Risk Management Market
A defining industry trend is the convergence of Supply Chain Visibility Software with generative AI models to automate Tier-N supplier mapping. Companies like Prewave GmbH and Interos Inc. are pioneering continuous monitoring solutions that ingest unstructured multilingual news and social data to flag labor violations or financial distress instantly. This shift moves procurement teams from reactive auditing to proactive, autonomous risk mitigation across global manufacturing ecosystems.
How did the COVID-19 pandemic affect the Artificial Intelligence-Powered Supplier Risk Management Market and drive its recovery trajectory?
The pandemic exposed severe vulnerabilities in single-source procurement models, permanently altering enterprise risk appetite and accelerating market adoption. Lockdowns across major Asian manufacturing hubs and unprecedented maritime bottlenecks forced C-suite executives to abandon legacy spreadsheets for automated intelligence tools. Consequently, the crisis catalyzed a sustained recovery trajectory, embedding Artificial Intelligence-Powered Supplier Risk Management as a boardroom-level priority for supply chain resilience and operational continuity.
Competitive benchmarking and strategic dynamics in the Artificial Intelligence-Powered Supplier Risk Management Market
The competitive landscape is characterized by a mix of enterprise resource planning giants and agile pure-play innovators. Enterprises like SAP SE and Oracle Corporation embed risk modules directly into procurement suites, whereas specialists such as EcoVadis SAS and Resilinc Corporation offer deep, domain-specific intelligence. Market concentration is moderate yet intensifying as established vendors pursue strategic acquisitions of niche AI startups to capture higher-margin compliance and ESG monitoring segments.
Executive summary of the Artificial Intelligence-Powered Supplier Risk Management Market
Driven by a robust CAGR of 22.35%, the Artificial Intelligence-Powered Supplier Risk Management Market is projected to surge from $5.06 Billion in 2026 to $20.77 Billion by 2033. This exponential trajectory reflects urgent corporate demand for automated financial, cybersecurity, and operational risk assessment tools. Stakeholders must prioritize cloud-based deployment models and advanced compliance monitoring to navigate increasingly volatile international trade corridors and stringent regulatory frameworks successfully.
Market forecast trajectory from 2027 to 2033
Our forecasting models project the market to expand aggressively from 2027 through 2033, culminating in a valuation of $20.77 Billion by the end of the forecast period. This growth is sustained by compounding investments in Third Party Risk Management Software across highly regulated sectors like banking and healthcare. As supply chain volatility becomes the baseline normal, enterprise spending on predictive analytics and automated mitigation services will outpace traditional IT budgets.
Segmentation analysis across end-users, services, software, components, applications, deployment modes, and enterprise sizes
The market breaks down across multiple vital vectors: By Component (Software, Services); By Software (Supplier Risk Assessment, Predictive Risk Analytics, Compliance Monitoring, Supply Chain Visibility, Third Party Risk Management); By Services (Consulting, Implementation, Integration, Managed, Support and Maintenance); By Application (Financial Risk Assessment, Compliance Management, Supplier Performance Evaluation, Cybersecurity Risk, Operational Risk); By Deployment Mode (Cloud, On Premises); By Enterprise Size (Large Enterprises, SMEs); and By End User (Manufacturing, Retail, Healthcare, BFSI, IT and Telecom, Energy and Utilities, Others). Each segment addresses distinct operational vulnerabilities, with cloud-based software leading adoption.
Regional market analysis and geographic distribution performance
Geographic performance highlights North America as the current revenue leader, driven by stringent federal compliance standards and early technology adoption among Fortune 500 manufacturers. Meanwhile, Europe represents the fastest-growing regional market, propelled by rigorous legislative frameworks mandating strict supply chain due diligence and carbon footprint disclosures. Asia-Pacific exhibits high growth potential due to its sprawling electronics and automotive manufacturing hubs requiring robust operational risk mitigation tools.
In-depth regional review of high-growth territories
A closer examination of European markets reveals that stringent local environmental mandates are forcing firms to deploy advanced ESG and compliance monitoring solutions rapidly. In North America, the focus centers heavily on cybersecurity risk and financial resilience, as enterprises grapple with intellectual property theft and tier-3 supplier insolvencies. Meanwhile, emerging industrial clusters in Southeast Asia are increasingly adopting mobile and cloud-based supplier evaluation platforms to integrate smoothly into Western multinational supply chains.
Company profiles and strategic positioning of leading industry participants
Market leaders leverage distinct strategic advantages to capture market share. Moody’s Corporation and Dun And Bradstreet Holdings Inc. utilize vast proprietary financial databases to bolster predictive risk analytics. Concurrently, innovators like Exiger LLC and Everstream Analytics GmbH apply advanced machine learning to map complex, multi-tier supply networks. Firms such as GEP Worldwide LLC and JAGGAER LLC integrate these intelligence feeds directly into source-to-pay workflows for seamless procurement execution.
Porter's Five Forces analysis of the Artificial Intelligence-Powered Supplier Risk Management sector
Bargaining power of suppliers is moderate, tempered by the proliferation of alternative open-source threat intelligence feeds. Threat of new entrants remains constrained by high capital requirements, complex algorithm training costs, and the strict data security accreditations required by global enterprises. Conversely, rivalry among existing market players is intense, compelling continuous feature innovation in predictive analytics and real-time operational risk alerting capabilities.
SWOT analysis of the Artificial Intelligence-Powered Supplier Risk Management Market
Strengths include high predictive accuracy and seamless enterprise software integration. Weaknesses stem from reliance on historical data and potential algorithmic bias. Opportunities abound in expanding SME adoption and automated Scope 3 carbon tracking. Threats involve evolving cybersecurity regulations and potential data sovereignty disputes across cross-border cloud deployments. Vendors addressing these structural hurdles will capture disproportionate market share through 2033.
Value chain analysis from raw materials to end-user deployment
The industry value chain begins with raw data acquisition—spanning IoT feeds, financial registries, and geopolitical news—processed through proprietary AI algorithms by software vendors. System integrators and consultants then deploy these solutions into corporate procurement workflows. Finally, end-users in sectors like healthcare and manufacturing utilize these insights to audit vendors, optimize inventory buffers, and ensure continuous component delivery despite localized supply disruptions.
Investment insights and high-potential strategic areas for stakeholders
Investors should focus capital deployment on cloud-native software providers specializing in predictive compliance and Scope 3 emissions tracking. High-potential areas include managed services tailored for resource-constrained small and medium enterprises, as well as AI integrations targeting cyber-supply chain vulnerabilities. Companies offering modular, API-first architectures will achieve faster enterprise deployment and higher customer lifetime value compared to legacy on-premise monoliths.
Conclusion and key takeaways for executive decision-makers
The data confirms that the Artificial Intelligence-Powered Supplier Risk Management Market is transitioning from a competitive differentiator to an essential enterprise operating requirement. Surging to $20.77 Billion by 2033 at a 22.35% CAGR, the sector offers immense potential for investors and technology buyers alike. Organizations must swiftly adopt advanced predictive platforms to safeguard against escalating geopolitical, financial, and operational vulnerabilities.
Research methodology for baseline estimates and data triangulation
Our research methodology employs a rigorous triangulation approach combining primary stakeholder interviews with supply chain executives, secondary macroeconomic data from global trade registries, and proprietary bottom-up econometric modeling. Baseline 2026 market sizing of $5.06 Billion was established by analyzing enterprise software licensing revenues, deployment expenditures, and specialized service contracts across all seven core end-user verticals globally.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics for artificial intelligence-powered supplier risk management across seven geographic regions, six software sub-categories, and seven major end-user industries from 2027 through 2033. Limitations include potential unforeseen macroeconomic shocks, rapid regulatory pivots in cross-border data transfer laws, and proprietary data confidentiality constraints among private technology vendors operating within the ecosystem.
Recent developments, strategic partnerships, and product launches in the sector
Recent industry momentum is defined by aggressive strategic partnerships and generative AI feature rollouts. Market participants such as Coupa Software Inc., Ivalua Inc., and Sphera Solutions Inc. have recently integrated advanced LLM-driven risk summaries into their source-to-pay engines. Furthermore, boutique innovators like Craft Technologies Inc. and Achilles Information Limited have secured vital funding rounds to expand their real-time ESG and financial health monitoring capabilities globally.